Personal Line of Credit (PLOC) in India: Definition, Benefits and Types
- What Is a Personal Line of Credit (PLOC)?
- Key Characteristics of a Personal Line of Credit
- How Does a Personal Line of Credit Work in India?
- Draw Period vs. Repayment Period
- Types of Line of Credit Loans Available in India
- Common Uses for a Personal Line of Credit
- How to qualify for a line of credit
- Personal Line of Credit vs Personal Loan vs Credit Card
- Pros and Cons of a Personal Line of Credit
- How do you get a personal line of credit?
- PLOC vs Personal Loan: Which Should You Choose?
- Frequently Asked Questions
Aman thought he needed money just once but his expenses kept coming in parts. First, there were medical bills, then costs for his freelance work, and later, gaps in his business cash flow. He took a personal loan, but the fixed amount didn’t really help it was either too much or not enough. Aman felt stuck managing it. Then he found a personal line of credit, which let him take money only when he needed it, making things much easier.
What Is a Personal Line of Credit (PLOC)?
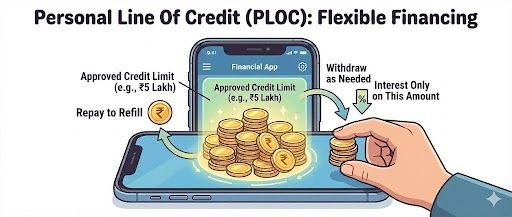
A personal line of credit is a pre-approved, revolving credit facility where the lender approves a maximum credit limit. You draw from this limit as needed once, partially, or multiple times and pay interest only on the amount actually withdrawn, not on the total sanctioned limit.
Once you repay what you've used, the limit is restored and becomes available again. This is the defining feature of revolving credit: unlike a personal loan (where repayment reduces a fixed balance), a PLOC continuously replenishes.
Key Characteristics of a Personal Line of Credit
- Flexible, On-Demand Withdrawals: Draw any amount up to your approved limit, as many times as needed during the draw period.
- Interest Only on Used Funds: Interest is calculated only on the withdrawn amount not the full sanctioned limit.
- Revolving Credit Limit: Repaid amounts become available again unlike a personal loan where the principal reduces permanently.
- Continuous Availability: Access funds throughout the approved tenure without submitting a fresh application each time.
How Does a Personal Line of Credit Work in India?
- Approval: Lender evaluates income, credit score, and repayment history and approves a credit limit.
- Withdrawal: You withdraw funds partially or fully using a linked account or designated disbursement method.
- Interest Accrual: Interest accrues daily on the outstanding drawn balance.
- Repayment: You repay the drawn amount (minimum due or full outstanding) as per agreed schedule.
- Limit Restoration: Repaid amounts are restored to your available credit limit.
Draw Period vs. Repayment Period
PLOCs typically operate in two stages. During the draw period, you can withdraw funds up to the approved limit. Interest is charged on outstanding balances. During the repayment period (which begins when the draw period ends or the credit line is closed), no new withdrawals are permitted, and the outstanding balance must be repaid per the agreed schedule.
In India, Credit lines are usually sanctioned for a fixed validity period, and many lenders renew them after reviewing your repayment record.
Types of Line of Credit Loans Available in India
- Personal Line of Credit: For individual borrowers covering personal expenses, medical bills, education, or home repairs. Can be secured (backed by an asset) or unsecured.
- Business Line of Credit: For businesses managing working capital, inventory, or operational cash flow. Can be secured or unsecured, depending on the lender and the business profile.
- Key distinction: Unsecured PLOCs require no collateral approval based on income, credit profile, and repayment history. Secured lines offer higher limits but introduce asset risk.
Common Uses for a Personal Line of Credit
- Medical treatment spread over multiple stages or visits
- Education expenses tuition instalments, certification fees, study materials
- Home renovation in phases not all at once
- Freelance or small business working capital needs
- Planned travel or lifestyle spending across multiple months
- Emergency buffer for unpredictable recurring expenses
How to qualify for a line of credit
Before applying for a personal line of credit, it helps to know lenders' requirements.
- Credit Score: A CIBIL score of 725 and above puts you in a strong position for approval and better terms. Scores under 725 are considered with other factors, but the odds and terms are less favourable.
- Income Stability: Most lenders consider a minimum monthly income of ₹15,000 to ₹30,000 depending on the credit limit you are applying for. Consistent and verifiable income improves confidence of the lender that repayments will be regular.
- Repayment History: A clean track record on existing loans and credit cards is a key factor. Past missed payments or defaults show higher risk and can affect both approval and the limit you are offered.
- Debt-to-Income Ratio: If a large portion of your monthly income is spent to pay several EMIs, lenders may hesitate to provide a loan. Lower existing obligations relative to your income make your position better in the loan application process.
- Employment Type: Loan applicants with consistent monthly income generally find the process very easy. Self-employed loan applicants have to provide additional documentation to establish income stability.
Personal Line of Credit vs Personal Loan vs Credit Card
| Feature | Personal Line of Credit (PLOC) | Personal Loan | Credit Card |
|---|---|---|---|
| Best Suited For | Variable, recurring needs | One-time, lump-sum expenses | Small, frequent purchases |
| Fund Access | Draw as needed up to limit | Full amount upfront | Purchase or cash advance only |
| Repayment | Flexible minimum due or full outstanding | Fixed EMIs each month | Flexible min. due or full payment |
| Interest Charged On | Withdrawn amount only | Outstanding principal (reducing balance) | Outstanding balance |
| Revolving | Yes, limit restores on repayment | No, balance only reduces | Yes, limit restores on repayment |
Pros and Cons of a Personal Line of Credit
Advantages
- Pay interest only on what you draw not the full sanctioned limit
- Funds are reusable no fresh application needed each time
- Ideal for expenses spread over time, not a single event
- Avoids over-borrowing draw exactly what you need, when you need it
Disadvantages
- Interest rates on PLOCs are often variable your cost can change over time
- Maintenance or annual fees may apply even on unused limits
- Not cost-effective for one-time lump-sum needs (a personal loan is more efficient)
- Requires strict financial discipline interest accrues daily on outstanding drawn balances
How do you get a personal line of credit?
Acquiring a personal line of credit includes many steps such as:
- Check your eligibility: Confirm basic details like age (21 to 58), a CIBIL score of 725 or more, and a minimum monthly income of ₹15,000 to ₹30,000, depending on the credit limit you need. A stronger credit profile improves both approval chances and the terms offered.
- Evaluate your budget: Calculate the credit amount you need and whether your current income and expenses let you manage repayments easily. Applying for more than your repayment capacity is a very common mistake.
- Prepare your documents: You have to submit certain documents digitally, such as PAN card, Aadhaar card, six months of bank statements, salary slips or ITR, and address proof. Most lenders complete verification digitally, so no branch visit or physical submission is needed.
- Submit your application: Apply through the lender's website or app with digital KYC. The lender then runs their credit and income assessment. Approval and activation will take around 2 to 7 business days, depending on how quickly verification completes.
PLOC vs Personal Loan: Which Should You Choose?
Choose a Personal Line of Credit if: your expenses are spread over time, unpredictable in quantum, and you need the flexibility to draw funds in multiple tranches without a fresh application.
Choose a Personal Loan if: you have a specific, defined one-time expense a medical bill, a purchase, a travel plan and want a fixed EMI repayment schedule with full amount disbursed upfront.
Hero FinCorp offers instant personal loans from ₹50,000 to ₹7 lakh, with approval in 10 minutes and same-day funds for eligible borrowers. The application is fully digital through the website or app.
Frequently Asked Questions
What is a personal line of credit (PLOC) in India?
A personal line of credit is a pre-approved revolving credit facility where you draw funds as needed up to an approved limit and pay interest only on the withdrawn amount. The limit restores as you repay.
Is a PLOC better than a personal loan?
It depends on your needs. For recurring or phased expenses, a PLOC is more efficient you avoid paying interest on funds you haven't used. For a one-time lump-sum need with a clear repayment plan, a personal loan is simpler and typically more cost-effective.
What CIBIL score is required for a personal line of credit?
A CIBIL score of 725 and above significantly improves approval chances and terms. Scores below this threshold may still be considered depending on income, employment stability, and overall credit profile.
What is the minimum income required for a PLOC in India?
Most lenders require a minimum monthly income of Rs 15,000 to Rs 30,000 for personal line of credit products. Requirements vary by lender and credit limit sought.
What happens if I don't use my approved line of credit?
Interest is not charged on unused portions of your credit limit. However, some lenders may charge an annual maintenance or commitment fee on the sanctioned facility, regardless of utilisation.
Does using a personal line of credit affect my credit score?
Yes, it affects your credit score in several ways. Applying may trigger a hard inquiry, which causes a small temporary dip. Once active, your credit utilisation ratio comes into play — using a large portion of your limit consistently may affect the score over time. Timely repayments help, while missed payments or high outstanding balances negatively affect your credit profile.
Is a personal line of credit available at Hero FinCorp?
Hero FinCorp offers fixed-amount personal loans from ₹50,000 to ₹7 lakh. A credit line is a separate product from other lenders.
Can I withdraw cash from a personal line of credit?
This depends on the lender. Some lines allow transfer to your bank account, while credit lines on UPI allow merchant payments only.
Disclaimer: The information provided in this blog post is intended for informational purposes only. The content is based on research and opinions available at the time of writing. While we strive to ensure accuracy, we do not claim to be exhaustive or definitive. Readers are advised to independently verify any details mentioned here, such as specifications, features, and availability, before making any decisions. Hero FinCorp does not take responsibility for any discrepancies, inaccuracies, or changes that may occur after the publication of this blog. The choice to rely on the information presented herein is at the reader's discretion, and we recommend consulting official sources and experts for the most up-to-date and accurate information about the featured products.